Google 账号支持自拍人脸登录
Google 账号加入了可选的人脸识别登录。用户向 Google 提供自拍视频,随后就可通过人脸识别登录。在人脸验证过程中 Google 可能会要求用户以特定方式转动头部,此举旨在防止深度伪造之类的身份冒用,确保用户当前确实在摄像头前。Google 需要保存用户的自拍视频以将其用于未来的登录验证。搜索巨人表示会对视频进行加密,且仅用于登录不会用于其它用途。如果用户改变主意,可以从 Google 帐户中删除相关视频。


(本文作者为 听风译码,钛媒体经授权发布)
文 | 听风译码
华为实习工资上热搜,可真正该慌的,不是没拿到那张 offer 的人。
这两天刷微博,一条热搜看得人心里一紧:#实习工资居然能到一万#。
说的是华为松山湖的实习生,有人日薪折算下来月薪已经过万;评论区接着冒出字节、腾讯的高薪实习岗,一水的”给钱大方”。
你大三还在为一份实习有没有补贴、够不够房租发愁的时候,有人已经拿着比不少正式员工还高的月薪,在改写”实习”这两个字的定义了。
但这件事,真的只是”别人家的孩子真牛”吗?
我看未必。它更像一面镜子,照出了一个正在发生、却很少有人直说的现实:
大厂和普通人之间那道分水岭,已经悄悄从”校招”提前到了”大三”。
是真的,但得先划清范围:它发生在头部大厂的特定岗位上,不是所有实习生都这样。
先给你一张不会被热搜误导的”实习薪资地图”。综合各招聘平台与在校生爆料,目前国内实习薪资大致分三档:
头部大厂的技术、算法、AI 岗,月给 8k 到 15k 不等,过万是这批岗位的正常水位;中厂、独角兽或一线城市普通互联网公司,实习补贴多在 3k 到 6k;而小微企业、本地公司、导师课题组,大多 0 到 2k,不少还要自己贴房租通勤。
这张地图的跨度,比很多人想象的大。为什么同样是”实习生”,收入差距能差出十倍?无非三个变量:城市(北上深给得起,二线普遍腰斩)、行业(互联网、金融高于传统制造)、岗种(写代码、做模型高于行政、运营)。
举个具体的:同样在深圳,大厂算法实习月给过万,而一家本地广告公司的文案实习可能只有 1500 还不含饭补。
热搜顶上来的是第一档里最亮眼的那几个,沉默的大多数其实在第三档。把第一档当成全体实习生的人生,是最容易掉进的坑。
可即便如此,这件事依然刺眼。因为在大多数人的经验里,实习等于”打杂 + 补贴几百块”,能开个实习证明就谢天谢地。当”实习月薪过万”撞上”实习补贴八百”,那种错位感才这么强。
但请先别急着焦虑。月薪过万的实习,绑定了名校背景、硬技术、大厂岗位三重门槛。
我们真正该琢磨的,不是”我为什么没拿到”,而是”为什么他们大三就拿到了,而我毕业才知道有这回事”。
大厂不是做慈善。肯给在校生开正式工级别的薪水,背后算的是三笔账,而且算得极清。
先看抢人前移。好苗子就那么多,AI、芯片、基础软件这些方向,一个靠谱的研究生,毕业时被十几家厂争。
与其等校招时血拼,不如大二大三就伸手锁定——用高薪提前买断你的”注意力”和”忠诚度”。你越早进我的池子,越不容易被对手挖走。
再看稀缺溢价。这轮薪资上涨,集中在算法、大模型、底层架构这类供需严重失衡的岗。一个能写推理优化的实习生,可能直接顶半个初级工程师的活。
市场价摆在那,不给够人早就跑了。说白了,不是”实习生值钱”,是”稀缺方向上的年轻人值钱”。
最后是培养即筛选。给高薪,实习生才愿意承受大厂那套高压节奏;同时,这也是最低成本的”长周期面试”。
你干三个月,公司把你摸得底朝天,比面试十轮都准。对大厂来说,这笔钱不是工资,是”试用期前置”的筛选费。
想明白这三笔账,你就懂了:那 1 万块,买的不是你现在的产出,是你未来的可能性。
如果只盯着数字看,这篇文章早该结束了。可我觉得,比工资更值得说的是另一件事。
真正的差距,从来不是那张工资条,而是你比别人晚知道了多少年。
我认识一个普通二本计算机专业的同学。他大二暑假还在送外卖攒学费,压根不知道有”暑期实习转正”这条路。
等到大三秋招,他才从舍友那听说:人家大二就进了某大厂实习,大三直接拿 return offer,秋招根本不用卷。
同一个宿舍,同样的智商,差的不是能力,是”早知道”和”刚知道”之间那两三年。
更隐蔽的是信息的”马太效应”。一线高校有校友群、有学长内推、有老师直接对接企业;内陆普通院校的学生,连”提前批”三个字可能都是刷社交媒体才第一次听见。
渠道本身就不平等,知道得晚,不是你笨,是你手里的情报网太薄。
还有资源差。一份大厂实习经历会滚雪球:下一份实习更好找,校招简历直接过初筛,面试官高看一眼。
而第一份实习就进了小公司打杂的人,想翻盘,得用成倍的努力去补那张”空白简历”。
不是普通人不行,是普通人的起跑信号,响得晚了一些。
写这些,不是为了吓你躺平。
月薪过万的实习依然是少数。绝大多数学长生在中小企业、在本地公司、在课题组里干活,补贴从几百到两三千不等,这才是沉默的大多数。
把第一档当成标准,只会让自己陷入无谓的自我怀疑。
而且大厂高薪岗对应的是极高强度。996 起步、KV 考核、随时可能被优化的试用期,那 1 万块是用青春和头发换的,远没有热搜看起来那么光鲜。
我见过拿了高薪实习的同学,三个月瘦了十斤,半夜在朋友圈发”撑不住但又不敢走”。
所以我得把话说全:分层在提前,是趋势;但”普通人没机会”,是错觉。 趋势提醒我们要清醒,错觉只会制造放弃。两者必须分开看。
另外提醒一句实务:实习生和正式员工在法律保障上并不完全一致,签协议时一定看清工时、补贴发放方式、是否买意外险。别被”月薪过万”冲昏头,落到纸面的条款才是真保障。
光焦虑没用,得给点能落地的。不管你是普通一本、二本,还是已经大三”醒晚了”,下面这些路都走得通——它们未必让你月薪过万,但能让你别再”刚知道”。
最该先补的,是信息差。别等毕业,大二就该盯起来了:各家官网的”校园招聘—实习生”入口、牛客网的实习板块、学校就业群的内推消息。
提前批、暑期实习、日常实习,名字不一样,全是机会。知道得早,就赢了一半。
比死磕公司更划算的,是选对赛道。技术、数据、产品这类岗溢价天然高;文科也别慌,商业分析、用户研究、内容运营一样有出路。
先想清楚”我想往哪个方向攒能力”,再去找对应的实习,比海投一百份”行政助理”有用得多。
简历空着的时候,用项目作品去填。写”认真负责、吃苦耐劳”,面试官一眼跳过;但你如果自己做过一个小工具、分析过一份公开数据、写过一篇有阅读量的深度稿,那就是硬通货。
项目不一定要惊天动地,但要能证明”你真的干过活”。
第一份实习进不了大厂,没关系,把它当跳板。小公司也能攒可量化的成果:你帮它涨了多少粉、省了多少钱、优化了哪个流程。把这些写进下一份简历,下次就能往更好的地方跳。
还有一件容易被忽略的事——经营你的”情报网”。加几个目标行业的交流群,关注几个靠谱的校招博主,哪怕只是每周刷一次牛客的实习版。
信息差不是一天补上的,是天天看、慢慢攒出来的。身边的人都在卷,但卷的前提是”知道往哪卷”。
最后,每份实习前先想清楚”我要学到什么”。别只问给多少钱。一份实习值不值,看三件事:能不能接触核心业务、有没有人带你、能不能写进简历当作品。
钱少但能学到东西的实习,长远看比钱多但只端茶倒水的更值钱。
实习不是为了那点钱,是为了用最低成本,试错出你到底适合什么。
写到这,我得补一刀,免得你把”进大厂拿高薪实习”当成唯一正解。
我另一个朋友,放弃了大厂低阶实习,留在一个十几人的创业公司跟老板做全栈。一年下来,他一个人扛了从前端到上线的整条链路,简历上写的是”独立负责一款产品的从 0 到 1″。
后来校招,他拿到的 offer 不比那些大厂实习生差。

大厂给你的是平台和光环,小公司给你的是”什么都得自己上”的全局能力。前者省心但容易被螺丝钉化,后者累但成长曲线陡。没有谁绝对更好,只有”哪个更适合现在的你”。
所以别被那 1 万块绑架了选择。有人适合去大厂镀金,有人适合在小地方练全活。看清自己的阶段和目标,比盲目追高薪重要得多。
前面说”看三件事”,太模糊。给你一个能直接用的评分框架:满分 10 分,每一项都问自己几个问题——
这份活和我想要的方向贴不贴?有没有人愿意带我、给我反馈?结束时我能不能说清楚”我做了 X,带来 Y”?这段经历写进简历,能不能帮我过初筛?最后,补贴够不够覆盖基本生活?
把这五个问题逐项打打分,8 分以上闭眼去,6 到 7 分能学东西也值得,5 分以下除非真缺经历否则慎重。这张表的意义,是让你别被”月薪过万”或”大厂光环”单独绑架——综合看,才看得清。
拿我那个二本同学举例。他第一段实习在小公司做数据标注:活儿沾边但不够核心,导师倒是真带,成果只能说”做了标注”,背书平平,还得自己倒贴。算下来刚好 5 分。
他当时就明白”这段只能当跳板”,于是逼自己攒了一份独立的数据分析报告,把”成果可量化”从 1 分拉到了 2 分。靠这份报告,下一段实习进了中厂。
你看,这张表不是用来算分的,是用来倒逼你想清楚:这段实习,我到底要带走什么。
说完怎么选,也得说清楚什么不能选。每年都有学生栽进差不多的几种坑里。
最典型的,是付费内推。凡是让你先交几千到几万”保证进大厂”的,基本是割韭菜——正规内推不收费,收费的多半是把你塞进边缘岗甚至假岗。记住一句话:真要你,不会先要你的钱。
还有挂名假实习。只挂公司名、不干实际活、不开真实证明,纯为简历好看。这种一旦被背调问出细节就露馅,反而毁信用。宁可去小公司真干两个月,也别挂名混三个月。
最要警惕的是押金和培训贷。以”岗前培训”为名让你签贷款协议、交押金的,直接拉黑。正规实习不会让你先掏钱;遇到这种,第一时间告诉学校就业中心。
很多人说”晚知道”,其实不是不知道,是没节奏。从大二到大三,照着这个节奏走,基本不会错过窗口。
大二上的秋天,别急着投,先把内功练起来:想清楚方向,动手做 1 个小项目,把简历初稿写出来。没作品就海投,投的往往也是打杂岗。
到了大二下,第一次窗口开了——盯日常实习和暑期实习提前批。大厂暑期实习通常在前一年底到当年春季开放,很多人就是这阶段拿到了大三暑假的 offer;错过这波,就得等秋季。
大三上是第二次窗口,秋招提前批和日常实习并行,大二下没拿到的,这是补救机会,同时开始把实习成果量化、准备校招简历。
再到大三下,最后冲刺:还没经历的抓紧找一段能写进简历的,已有经历的冲 return offer 或更好的暑期岗,给秋招铺路。
关键就一句:大厂的暑期实习,往往在大二下就要动手。你等到大三才问”去哪投”,窗口已经关了一半。 时间线本身,就是一种信息差。
得说点扎心的。为什么有人大二就知道提前批,有人大三还懵着?很大程度上,是因为背后的家庭资源不同。
有条件的家庭,父母本身在职场、有圈子,孩子从小耳濡目染”该怎么规划”;普通家庭的孩子,父母可能自己都没进过写字楼,根本给不了这类信息。这不是谁的错,是真实的起点差异。
但也正因如此,普通家庭的孩子更该主动补这张网。学校就业指导中心、免费的校招公众号、学长学姐的分享,这些都是不花钱的情报来源。
信息差可以靠主动去填,资源差不能完全抹平,但能缩小。
我那个二本逆袭的同学,起点不高,父母都是工地上的人,根本给不了职场信息。但他做对了一件事:厚着脸皮加了十几个同行的学长微信,一个个请教”你当时怎么找的实习”。
前三个不回,第四个回了”去牛客看实习版”。他就真天天刷,刷出第一个面试。笨办法,但管用。普通家庭的孩子,往往差的就是这层”脸皮”和”主动”。
写这篇,不是要你羡慕那张过万的工资条,更不是劝你焦虑。
我是想说:机会的窗口,确实在变小、在提前。以前我们觉得”毕业再想找工作”,现在大二大三就在分岔了。越早看清这张地图,你越不会被热搜牵着情绪走。
月薪过万不是终点,也不是评判你行不行的唯一标准。它只是个信号——提醒我们,该为自己多操一点心了。
热搜会过去,但分层的趋势不会;你能做的,是别让自己醒得太晚。
你实习拿多少?或者,你身边有月薪过万的实习生吗?评论区聊聊,说说你看到的真实情况。
更多精彩内容,关注钛媒体微信号(ID:taimeiti),或者下载钛媒体App

Nexfin News — China’s lithium battery industry is undergoing a rite of passage, transitioning from wild expansion to disciplined competition. In the first half of the year, a rare divergence between surging corporate earnings and falling stock prices brought a permanent shift in the sector’s underlying dynamics into sharp focus.
By mid-July, A-share lithium battery stocks pulled back despite dramatic midyear earnings forecasts. Tianqi Lithium projected net profit growth of up to 4,935% year-over-year, EVE Energy forecast a 95% to 110% increase, and both Sunwoda and REPT BATTERO turned profitable again. Across the supply chain—from upstream lithium salts to downstream battery makers—most companies reported substantial operational gains.
Yet robust earnings failed to stop equity valuations from sliding. On July 8, Chengxin Lithium hit its daily downside limit, Yahua Group dropped over 15%, and Tinci Materials saw more than 30 billion yuan in market value evaporate within a week. Ganfeng Lithium has fallen roughly 38% from its peak, while market leader CATL is down about 20%.
The immediate trigger for the selloff was the resumption of operations at CATL’s Jianxiawo lithium mine. On June 29, the mine secured its safety production permit, which was officially posted on the Credit China website on July 7. The site—the world’s largest single lepidolite mine—had been idle for over ten months. With an annual capacity of roughly 100,000 metric tons of lithium carbonate, it previously accounted for 8% to 10% of China’s total output. Its return brings over 45,000 tons of additional supply in the second half of the year, hitting elevated lithium prices head-on. Futures markets reacted instantly: on June 18, as restart speculation grew, the main lithium carbonate contract fell 6.58% in a single session, beginning a steady slide from its May high of 205,000 yuan per ton.
This stark contrast between thriving industrial output and falling stock prices coincided on the surface with lithium carbonate pulling back rapidly from its May peak of 200,000 yuan per ton to 151,000 yuan. But a more critical question remains: is this the sign of a cyclical peak, or is the industry undergoing a profound revaluation?
Answering that requires stepping back to examine the paradigm shift that unfolded across the lithium battery sector between 2025 and 2026. The essence of this shift is not the fluctuation of any single price signal, but a permanent realignment of the industry’s competitive playbook—moving from “who expands the fastest” to “who possesses technology, steady profits, and global compliance capabilities.”
In late June 2025, battery-grade lithium carbonate dropped below 60,000 yuan per ton, touching a three-year low of 59,900 yuan. Lithium salt producers across the sector incurred heavy losses, forcing widespread shutdowns among small and medium-sized manufacturers. From Australian hard-rock mines and small African projects to domestic lepidolite producers, virtually all marginal capacity went offline that summer. A two-and-a-half-year price slump accomplished its single necessary function: clearing out excess supply.

By the fourth quarter of 2025, supply and demand dynamics reversed faster than the market had anticipated.
The initial spark came from energy storage demand. Data from research firms including InfoLink show that global energy storage cell shipments reached roughly 610 GWh in 2025, up over 90% year-over-year, with fourth-quarter volumes alone topping 200 GWh. Production schedules showed energy storage cells clearing lithium carbonate inventories at an accelerating quarter-over-quarter pace. As growth in electric vehicle batteries moderated, energy storage stepped in not just to absorb excess capacity, but as the industry’s primary growth engine.
Surging demand was only half the story; supply contracted just as sharply. Small African mines and high-cost domestic lepidolite operations exited the market. Meanwhile, Zimbabwe announced a temporary suspension of lithium concentrate exports in February—a country that accounted for 15.5% of China’s lithium concentrate imports in 2025. Although Australia remained the primary pillar of China’s upstream raw material supply at over 50%, the policy further tightened market expectations surrounding upstream supply. Zimbabwe’s Ministry of Mines later confirmed that a formal export ban would take effect in January 2027.
The tension between supply and demand peaked with the onset of a structural global deficit. Morgan Stanley estimated in early 2026 that the global market would face a shortfall of roughly 100,000 metric tons of lithium carbonate equivalent (LCE) for the year. Soochow Securities calculated total annual lithium mine supply at approximately 2.14 million tons, representing 440,000 tons of new capacity—most of which was not slated to come online until after the third quarter. That timing gap fueled the price rally during the first half of the year.
Driven by these converging forces and inventory restocking across midstream channels, lithium carbonate surged from 70,000 yuan per ton in October 2025 to 200,000 yuan by May 2026. Unlike the speculative frenzy that drove prices to 600,000 yuan in 2022, this recovery occurred after capacity had been fully built out, anchored firmly by real end-user demand.
Gaogong Industry Research Institute (GGII) summarized the shift: “This is not a bubble, but a return to fundamental value. The structural surge in energy storage demand, combined with supply-side consolidation, has redefined a rational price band for lithium.”
Prices doubled quickly due to market sentiment and downstream stockpiling. July’s price correction reflected two main factors: the gradual release of new supply and downstream resistance to inflated raw material costs. Analysts generally expect lithium carbonate to trade within a median range of 120,000 to 160,000 yuan per ton for the full year—a price level that keeps most producers profitable without triggering another round of reckless expansion.
In the first half of 2026, China’s energy storage battery shipments reached roughly 485 GWh, a year-over-year increase of over 80%. Over the same period, power battery shipments totaled roughly 630 GWh, up over 30%. The gap between the two segments is narrowing rapidly.
Structural figures are even more telling. In the first quarter of 2026, Chinese energy storage battery shipments totaled about 209 GWh, up 115% year-over-year and accounting for roughly 40% of total lithium battery shipments. By June, energy storage cells made up nearly 41% of monthly production schedules—up from around 30% a year earlier.
According to InfoLink, full-year energy storage cell shipments in 2025 reached roughly 610 GWh, approaching 70% of power battery shipments over the same timeframe. Energy storage is no longer a side business for battery makers; it has emerged as an independent market reshaping demand across the industry.
Behind this market realignment lies a fundamental shift in purchasing drivers. Before 2024, domestic energy storage growth was driven primarily by mandatory integration policies, which required wind and solar projects to install storage capacity. That regulatory setup created low-quality demand, leading to poor utilization, weak financial returns, and inconsistent cell quality.
Between 2025 and 2026, market dynamics pivoted from regulatory compliance to commercial economics.
The shift first materialized in the domestic market. In early 2026, the National Development and Reform Commission and the National Energy Administration jointly issued new capacity pricing regulations (NDRC Pricing [2026] No. 114), establishing a national capacity tariff mechanism for standalone energy storage facilities. Local standards were set between 165 and 330 yuan per kilowatt-year, depending on the province. Surveys by Soochow Securities indicated that internal rates of return (IRR) for storage stations in several provinces crossed the 6% threshold required for commercial viability, especially where peak-to-valley price spreads exceeded 0.3 yuan per kWh. IRRs for top-tier projects reached as high as 10%, fundamentally improving overall demand quality.
This domestic turning point coincided with an explosion in international demand. Major solar-plus-storage projects launched across the Middle East, particularly in Saudi Arabia and the United Arab Emirates, with individual project capacities regularly reaching several gigawatt-hours. In emerging markets across Australia, Southeast Asia, and Africa, weak power grids and rising renewable energy penetration transformed energy storage from an optional luxury into a necessity. Soochow Securities calculated that utility-scale storage installations in emerging markets grew 233% year-over-year in 2025, with an additional 69% increase projected for 2026. In Europe, energy security concerns and green energy quotas kept commercial, industrial, and residential demand robust.
GGII projects that global energy storage battery shipments in 2026 will reach 800 to 1,100 GWh, representing year-over-year growth of 30% to 70%. Even at the mid-point estimate of 900 GWh, energy storage output is positioned to approach or match power battery production this year.
As the industry’s primary growth engine shifts, its core operational requirements are evolving as well. Power battery demand is dominated by automakers, whose priority is cost efficiency. The customer base for energy storage, however, is far more diverse: utility operators prioritize long cycle life and safety, data center owners require high discharge rates and extreme reliability, and overseas projects demand lifecycle compliance and supply-chain traceability. Winning in these markets requires technological adaptation, solid project execution, and international compliance capabilities rather than sheer scale.
Evaluating battery utilization rates requires a closer look at the underlying numbers.
In May 2026, the single-month installation rate for Chinese power batteries dropped to roughly 38%. Over the first five months of the year, cumulative power battery installations totaled 259 GWh against 863 GWh produced—yielding an overall utilization rate of about 30%. Factory output continues to outpace vehicle installations, leaving a substantial share of manufacturing lines underutilized.
The five-year trajectory of Chinese power battery installation rates tells a clear story: 70% in 2021, 54% in 2022, roughly 52% in 2023, 50% in 2024, 44% in 2025, and 38% by May 2026.
This steady decline in installation rates offers clear evidence of an industry transitioning from rapid early growth into maturity.
Yet labeling the sector simply as oversupplied misses crucial nuances. The market is not experiencing a uniform glut; rather, it is undergoing sharp structural polarization.
High-end shortages coexist alongside low-end surpluses. Demand for premium batteries with energy densities above 160 Wh/kg—primarily ternary chemistries—rebounded sharply, rising from a 6% market share in 2025 to 11%. Meanwhile, low-end products under 125 Wh/kg have effectively been phased out.
Demand has also diverged sharply between commercial and passenger vehicles. Driven by subsidy policies, battery demand for electric heavy trucks and delivery vans surged, with battery consumption for electric cargo vans rising 169% year-over-year. By contrast, electric buses—once the industry’s primary market—fell to fifth place.
While market leadership remains dynamic, the nature of competitive moats is shifting. CATL and BYD together retain a 68% market share, but second-tier players like Gotion High-tech, EVE Energy, Svolt Energy, and Hithium are making gains. Competition is shifting from pure capacity expansion to technological differentiation and operating margins.
From another perspective, declining installation rates are a natural hallmark of industry maturity. As annual growth moderates, a drop in capacity utilization from 70% to 40% is to be expected. While systemic capacity pressures continue to weigh on industry-wide profitability, and smaller players face ongoing price competition, market leaders retain the balance sheet strength to navigate the transition. As top-line growth slows, manufacturers lacking proprietary technology, accumulated capital, or global compliance infrastructure risk being squeezed out.
This shift explains recent strategic course corrections by major capital allocators. Anode producer Sinomatech canceled a 10.3 billion yuan expansion, cathode supplier Dynanonic abandoned a 10 billion yuan project, and separator manufacturer Semcorp terminated a roughly 2 billion yuan facility in Malaysia. Top-tier players reining in massive investments is a classic sign of an industry transitioning from early expansion to financial discipline.
This reallocation of capital does not mean expansion has halted entirely. In the first half of 2026, manufacturers announced over 65 new planned projects representing more than 1,500 GWh of capacity and over 220 billion yuan in total investment. Hunan Yuneng disclosed a 24 billion yuan expansion, while Yahua Group announced additional capacity in Zimbabwe. Expansion continues, but the prerequisites have changed: only enterprises with strong technical barriers, cash reserves, and global compliance infrastructure are positioned to invest while competitors scale back.
If the period between 2022 and 2024 was defined by a race for manufacturing scale, 2025 and 2026 have marked a pivot toward technological differentiation across three distinct fronts.
The central operational focus for the energy storage supply chain in 2026 has been a structural shortage of 314Ah cells rather than short-term price swings in raw lithium. By March, average spot prices for 314Ah cells from tier-one manufacturers approached 0.40 yuan per Wh, with small-lot orders reaching 0.45 yuan per Wh—a surge of over 25% within six months compared to the 0.30 to 0.34 yuan per Wh seen in August 2025.
The immediate driver was rising raw lithium costs—at 180,000 yuan per ton of lithium carbonate, theoretical cell production costs sit between 0.35 and 0.38 yuan per Wh. However, the root cause was a supply gap during the industry’s transition to larger formats. As manufacturers shift from 280Ah and 314Ah form factors toward 500Ah+ designs, investment in legacy 314Ah production lines has largely ceased. Because next-generation 500Ah+ cell capacity will not scale up until late 2026, production ramps and customer testing created a temporary bottleneck.
During this supply gap, the deficit widened significantly, pushing delivery timelines for select orders into 2027.
This dynamic reflects a clear shift in industry economics: market returns are no longer guaranteed simply by bringing capacity online, but by executing format transitions ahead of competitors. CATL has already deployed its 587Ah cell in a 2.4 GWh standalone storage project in Inner Mongolia, while EVE Energy has accelerated mass production of its 628Ah format. With the shift toward larger cell formats underway, manufacturing execution is everything.
While 314Ah supply constraints present an immediate operational challenge, solid-state technology represents the long-term competitive battlefield.
Although 2026 has been touted as the inaugural year for commercial solid-state battery deployment, that label requires qualification: current production consists almost entirely of semi-solid (hybrid liquid-solid) chemistries. Models including the NIO ET9, MG4, GAC Hyper, and Chery vehicles have entered the market equipped with semi-solid packs featuring energy densities between 350 and 400 Wh/kg. Because these designs remain compatible with over 90% of existing liquid battery production lines, retooling costs remain manageable and rollout schedules are accelerating.
However, the commercial reality of all-solid-state technology remains far more complex than vehicle showroom specifications suggest.
In March 2026, Ouyang Minggao, an academician at the Chinese Academy of Sciences, offered a candid assessment: “To be prudent, it is best not to commercialize all-solid-state battery vehicles over the next two years.”
He cited three major technical hurdles: solid-solid interface stability, where microscopic gaps between solid electrolytes and electrodes cause internal resistance to spike; lithium dendrite formation and safety risks; and the environmental volatility of sulfide electrolytes, which decompose upon exposure to moisture and demand strict manufacturing conditions.
Industry leaders report steady if measured progress. CATL’s sulfide-based solid-state cell has surpassed an energy density of 500 Wh/kg, with small-scale production anticipated in 2027. BYD’s 20 GWh facility in Chongqing is scheduled to begin semi-solid production in the third quarter of 2026, targeting pilot runs for all-solid-state cells in 2027. Gotion High-tech plans to initiate operations on a 2 GWh solid-state line by late 2026, while EVE Energy has produced sample 60Ah solid-state cells.
A clear timeline has taken shape: 2026 is focused on pilot line verification, 2027 on vehicle testing, and 2030 on potential large-scale commercialization. The implementation of recommended national standard GB/T 43568-2026 (Solid-State Batteries for Electric Vehicles) on July 1, 2026, established an initial regulatory framework for long-term development.
Ultimately, 2026 marks less the mass adoption of solid-state technology than a recalibration of market expectations.
Meanwhile, an underappreciated demand driver is quietly gathering momentum.
In the first five months of 2026, global energy storage shipments for AI data centers (AIDC) reached 10 GWh, surpassing total volume for all of 2025. Industry research firms project that global AIDC storage demand will reach 300 to 400 GWh by 2030—more than twenty times its 2025 level.
Capital deployment in the segment is ramping up. CATL invested roughly 4.1 billion yuan to acquire a strategic stake in Senter Power to secure positioning in high-voltage DC power distribution for data centers, while winning a bid for a 2 GW / 4 GWh storage project at a computing center in Guizhou. Fluence signed agreements covering a 12 GW pipeline of potential projects with two major U.S. cloud providers, LG secured eight data center storage contracts totaling 6 GWh—including projects for Oracle—and Panasonic announced 350 billion yen in battery investment aimed at tripling its data center storage revenue.
The expansion of AIDC storage is driven by a widening gap between AI computing power demands and utility grid capacity. Power consumption per rack in modern AI facilities has jumped from 5–8 kW in traditional data centers to 40–100 kW, while grid connection approvals and capacity upgrades often take three to five years. Onsite battery systems serve both as backup power and as a bridge to accelerate facility commissioning.
Energy storage is moving from an auxiliary fallback to an integrated structural component of data centers. Following NVIDIA’s October 2025 announcement of an 800V DC power architecture—designed to phase out diesel generators and legacy uninterruptible power supplies (UPS)—storage systems are being wired directly into primary distribution networks.
This shift expands the market beyond traditional buyers like power utilities and renewable energy developers to encompass cloud providers and infrastructure operators, establishing a distinct category of demand.
While domestic market consolidation marks the industry’s initial transition to maturity, international expansion presents a secondary test. Tariff structures, raw material access, and regulatory standards are tightening concurrently across major export markets.
Trade barriers represent the most immediate hurdle. The European Union’s countervailing duties on Chinese battery electric vehicles have been in effect for five years and are expanding to include plug-in hybrids. In the United States, the Inflation Reduction Act continues to raise domestic content requirements for power and energy storage batteries. Concurrently, China has reduced its export tax rebates for batteries from 9% to 6% as of April 2026, with complete elimination scheduled for January 2027. Rising trade costs are accelerating a shift from direct product exports to localized overseas manufacturing.
At the same time, competition over raw materials is intensifying. The U.S.-led Minerals Security Partnership continues work to build key mineral supply chains outside China, while changing rules in jurisdictions like Zimbabwe highlight shifting export policies. Strategic positioning across raw material supply chains remains an ongoing operational priority.
Regulatory compliance presents a quieter but more complex technical hurdle. The European Union’s Battery Passport regulations will become mandatory on February 18, 2027, requiring detailed disclosure of lifecycle carbon footprints, material origins, and recycled content percentages. The impact of these rules depends heavily on how accounting frameworks are defined; systematic discrepancies in baseline emissions databases regarding Chinese energy mixes or manufacturing processes could affect market access.
In response, leading Chinese manufacturers are moving from passive compliance to active engagement with international standards. CATL has partnered with BMW and Germany’s Catena-X network to help establish over 90 baseline carbon accounting metrics. BYD invested over 100 million yuan to develop its “i-Carbon Chain” platform for digital carbon tracking across its supply chain. Similarly, REPT BATTERO collaborated with TÜV Rheinland and Circulor on a battery passport initiative, securing third-party verification for 98 independent datasets from an EU Notified Body.
Overseas manufacturing footprints are expanding in tandem: CATL’s production complex in Hungary, BYD’s plant in Brazil, Gotion High-tech’s joint venture in the United States, and Envision AESC’s gigafactory in Spain. Chinese battery makers are transitioning from a model of centralized domestic production for export toward localized manufacturing aligned with international standards.
This next phase of international expansion hinges on regulatory transparency, supply chain control, and deep local integration.
In July 2026, as equity valuations diverged from corporate earnings across the lithium sector, market participants wrestled with where the industry stands in its broader evolution.
The most visible change is the shift in growth drivers. With energy storage shipments reaching 485 GWh in the first half of the year to account for over 40% of total output, the gap between storage and mobility applications is closing rapidly. This demand-side pivot coincides with capacity rebalancing on the supply side, where power battery installation rates have adjusted from 70% down to the 30%–40% range, signaling an end to early, unbridled expansion while overall margins remain under pressure.
These structural shifts are redefining entry barriers across the market. With 314Ah cell prices rising over 25% in six months and AIDC storage demand expanding rapidly, technical capabilities are increasingly determining market positioning. As national standards for solid-state technology take effect and EU Battery Passport deadlines approach, regulatory compliance has become a baseline operational requirement.
The trajectory of lithium carbonate—falling to 60,000 yuan, rebounding to 200,000, and settling near 150,000—reflects a market seeking equilibrium.
This broader transition was highlighted by a joint policy announcement on July 18, when three Chinese government ministries introduced a new consumption tax structure for batteries. Effective September 1, lithium-ion batteries are subject to a 2% consumption tax, rising to 4% in September 2027, while sodium-ion and solid-state batteries remain exempt through the end of 2028. The policy ends a tax exemption for lithium batteries that spanned more than a decade. Phasing in taxation uses fiscal policy to encourage capacity optimization and technological upgrading by taxing established chemistries while incentivizing next-generation alternatives. For second-tier cell makers operating on narrow margins, the 2% tax burden—equivalent to roughly 0.007 to 0.008 yuan per Wh—will further compress operating margins, reinforcing market consolidation around capitalized leaders.
For China’s lithium battery industry, 2026 represents a clear inflection point. Enterprises equipped with proprietary technology, international compliance frameworks, and established brand equity face a broader global landscape as the sector matures. Conversely, manufacturers reliant on single customers, lacking technical moats, or unable to meet evolving compliance standards face mounting pressure.
The early expansion phase of the lithium battery industry has drawn to a close. Its mature chapter is just beginning.
(This article was first published on the TMTPost App. Author | AGI-Signal, Editor | Zhao Hongyu)
更多精彩内容,关注钛媒体微信号(ID:taimeiti),或者下载钛媒体App

(本文作者为 听筒Tech,钛媒体经授权发布)
文 | 听筒Tech(ID:tingtongtech),作者 | 杨 林,编辑 | 饶霞飞
北京时间7月23日凌晨,美股科技巨头谷歌母公司Alphabet和特斯拉,几乎同时交出了2026年第二季度成绩单。
单看营收数字,两家公司都堪称“优等生”。
诸如,Alphabet二季度营收1197.96亿美元,同比增长24%,连续第12个季度实现两位数增长。谷歌云更是飙升82%至248亿美元,成为亮眼的增长点。
特斯拉也是“史上最强”,二季度营收282.36亿美元,同比增长26%,创下三年来最高增速。
然而,资本并没有为这两份成绩单喝彩。
财报发布后,谷歌盘后一度跌近5%,特斯拉盘后跌超4%。市场的焦虑,不止谷歌净利润水分巨大,抑或特斯拉在汽车价格战漩涡中,持续被侵蚀毛利。
更重要的是,不管是谷歌还是特斯拉,AI投入正在以惊人的速度烧钱,让两家巨头同步出现首次现金流转负。
过去,资本愿意容忍投入;但现在,市场开始警惕,海量的资本开支,到底什么时候才能兑现稳定的盈利。
显然,市场给出了一个更直接的命题,AI大跃进下,连全球最赚钱的科技巨头,都开始扛不住了。
可以说,两家都有光鲜的营收,但遮不住“内出血”。
先看谷歌。
1198亿美元的季度营收,净利润1121亿美元,同比暴增298%,单看这几个数,谷歌这一季度的表现,可谓夯爆了。
但仔细一看,谷歌净利润的暴增,主要依靠约990亿美元的股权投资收益撑着,包括主要持有Anthropic、SpaceX等公司的股权浮盈。
去掉这些“纸上富贵”,调整后,谷歌每股收益为2.85美元,低于此前华尔街预期的2.89美元。
让市场更倒吸一口凉气的,是现金流。
本季度,谷歌资本支出449.2亿美元,同比几乎翻了一倍。结果,这直接让自由现金流直接变成了负59亿美元。
这也是自谷歌上市以来,头一回单季自由现金流转负。简单说,谷歌一个季度花掉的钱,比赚进来的还多出59亿美元。
在财报电话会上,谷歌首席财务官阿什肯纳齐不仅没有安抚,反而“补了一刀”。他指出,谷歌预计全年资本支出指引刚上调到1950亿至2050亿美元,而且2027年还要“显著”增加。
Investing.com分析师托马斯·蒙泰罗这样评价,“市场上最可靠的现金流创造者,现在支出超过了收入。”
为了填这个“坑”,谷歌甚至都出去“借钱”了。财报数据显示,谷歌近期增发了496亿美元股票,同时,又发了203亿美元债券。
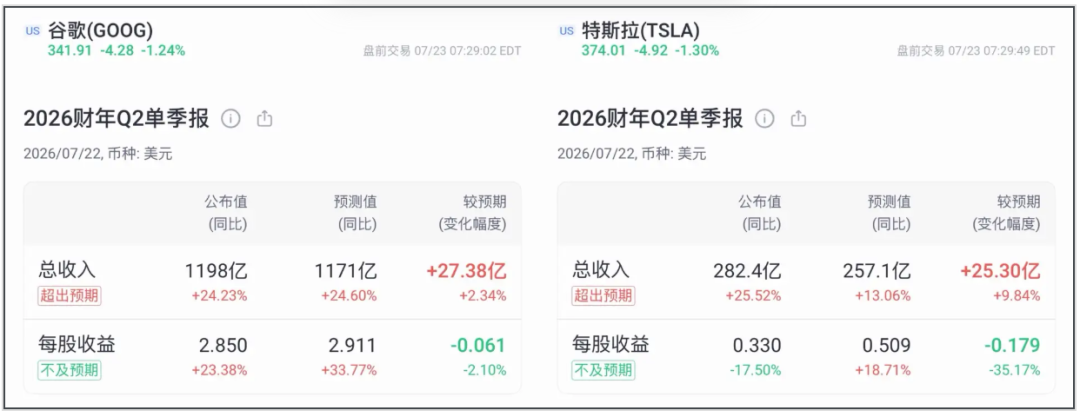
图:谷歌和特斯拉财报概要
来源:老虎证券 《听筒Tech》截图
再看特斯拉,处境就更拧巴了。
车卖爆了,钱却没赚到。
二季度,特斯拉交付了48万辆,同比增长25%,创历史新高。但归属于普通股股东的净利润只有11.14亿美元,同比下滑了5%。调整后每股收益0.33美元,也比市场预期的0.51美元,整整低了35%。
利润去哪了?答案之一是,被运营费吃掉了。
二季度,特斯拉运营费用同比飙升47%,达43.5亿美元。这让运营利润率,从去年同期的4.1%直接变成了1.4%。CFO塔内贾还补了一句,这费用,今年往后只会更高。
一边是暴涨的运营费,一边是快速推高的资本支出。财报数据显示,二季度特斯拉资本支出57.89亿美元,同比暴增了142%。
这里的花费,主要包括得州工厂的Dojo超算集群在扩建,Giga Texas的电池产线在铺设,以及Robotaxi车队在美国多个城市跑测试,Optimus机器人的量产线还在不断返工和调试。
在电话会上,马斯克罕见地倒了一次苦水,他表示,Optimus是特斯拉有史以来最难量产的玩意儿,“造车我们可以去外面买轮子、买后视镜,但机器人没有供应链。所有东西全得从零开始自己造。”
这也让特斯拉二季度自由现金流,从一季度的正14.4亿美元,直接变成负10.9亿美元,也是两年多来,特斯拉头一回单季自由现金流转负。
事实上,让谷歌和特斯拉都陷入怪圈的,主要原因是,目前正在投入的AI或机器人行业,仿佛一个无底洞,导致账上没什么余粮。
谷歌是不折不扣的AI基建狂魔,投入也不是从今年开始的。
2023年,Alphabet的资本支出是323亿美元。2024年,这个数字跳到了525亿美元。到了2025年,谷歌全年资本支出飙升至914.5亿美元,几乎全部投向了AI基础设施。
但这一切,跟2026年比起来都只是“开胃菜”。
今年2月,谷歌预计2026年资本支出为1750亿至1850亿美元。到了今年二季度,这个指引又被上调到了1950亿-2050亿美元。
钱都烧哪儿了?二季度,谷歌449亿美元的资本支出,约60%砸向了服务器,40%砸向了数据中心和网络设备。
此外,谷歌正在全球范围内扩建数据中心、批量采购TPU和英伟达加速芯片、搭建Gemini训练集群,扩充Virgo超算网络。
现在,Gemini模型API每分钟能处理220亿个Token;Gemini App月活用户达到9.5亿;云业务积压订单突破5140亿美元。但这些成果距离变成真金白银的利润,还有相当长的路。
面对分析师追问的“啥时候能回本”,谷歌CEO皮查伊也承认,“回报尚处于早期。”
再来看特斯拉。
事实上,如果说谷歌的AI大跃进是“广撒网”,那特斯拉就是在“赌命”。
2025年,特斯拉全年营收首次下滑,汽车业务天花板越来越近,马斯克决定转向“物理世界AI公司”。2026年初,马斯克直接宣布,未来以AI和机器人为核心业务重心,不再追求更大的汽车销售规模。
为撕开AI增长的口子,早在公司宣布调整之前,2024年特斯拉就在AI领域投了约100亿美元,2025年约85亿美元,到了2026年,这个数字直接被拉到超过250亿美元,几乎是2025年的三倍。
而这250亿美元,将近有200亿美元直接划给了AI相关项目,包括Dojo算力、数据中心、Robotaxi自动驾驶出租车、Optimus人形机器人。
到了2026年二季度,特斯拉资本支出为57.89亿美元,同比暴增142%。电话会上,马斯克重申了今年资本支出预计超250亿美元,未来两至三年还将持续增长。
同时,为了支撑这场豪赌,特斯拉正在寻求建立高达300亿美元的债务融资额度。
但问题在于,投入在狂奔,回报还在路上。
这基于一些现实。诸如,Robotaxi服务目前在奥斯汀、达拉斯、休斯顿运营,车队规模不到Waymo的零头;Optimus连量产线都在返工调试。
虽然,FSD活跃订阅量约150万,同比增长了56%,但这点收入,跟AI资本支出相比,简直杯水车薪。
特斯拉CFO塔内贾坦言,公司正处于“大规模投资周期”中。而摩根士丹利分析师说得客气,但也更直白,“资本支出翻倍、自由现金流转负,投资者盯的是这笔钱,到底能不能加固特斯拉的AI护城河。”
整体来看,不管是谷歌还是特斯拉,都选择了不同的AI路径。但殊途同归的是,这场AI投入的跃进,共识已经无比强烈,且烧钱速度,也清晰可见。
市场的感觉也越来越强烈,在这个AI集体奔跑的时代,行业是否正在制造一场集体性的财务幻觉?
谷歌、特斯拉之外,将视线拉回国内,同样的剧本也在上演。
公开的资料显示,字节跳动正在讨论将2026年资本开支提升至最高700亿美元,资金全部砸向数据中心和AI算力基础设施。
还有报道提及,为了给“军备竞赛”补充弹药,字节正在与多家银行洽谈新增约200亿美元的离岸贷款。
阿里方面,CEO吴泳铭曾明确表示,面向未来五年,AI基建投入资金会“远远超过”此前提出的三年3800亿元规划。但代价是,仅在2026财年第四季度,阿里经营亏损8.48亿元,自由现金流为流出173亿元。
腾讯方面,2026年一季度,腾讯AI相关资本开支高达370亿元,创单季新高,预计全年AI开支约900亿-1000亿元。与此同时,美银证券也将腾讯2026年资本开支预测上调至1850亿元。
全行业都在狂奔,但资本的耐心,却在递减。
Investing.com分析师直接表示,“只要营收持续增长,投资者还能忍。但资本成本是现实的,每个季度的容错空间都在缩小。”
华尔街的分歧也越来越大。
BCA Research首席经济学家彼得·贝雷津认为,美股正处于“盈利泡沫”阶段,芯片销售会直接增加供应商收入和利润,而云计算企业购买芯片通常作为资本开支处理,因此财报利润增长可能高于实际现金流改善。
对于市场的分化,诸多分析认为,行业“耐心不足”,主要原因在于,过去市场愿意为“颠覆性创新”买单,容忍度极高。但2026年的今天,高利率环境没根本改变,钱依然很贵。
一个最直接的表现就是,资本快速作出了反应。
财报发出后,谷歌盘后跌近5%,特斯拉盘后跌超4%,投资者直接表达了对“增支不增现”的担忧。
更耐人寻味的是,在谷歌和特斯拉财报发布不久后,DeepSeek创始人梁文锋此前一次长达4小时的投资人会议内容在业内流传,他在会上反复强调一个词,克制。
梁文锋的说法是,“克制是一种战略”。他这样解释,“我毫不怀疑AGI会有非常大的商业价值。在这个基础上,我优先考虑的不是多拿份额,而是增加做成的概率。你越克制,就越有可能做成这件事。”
在梁文锋的思考框架中,AGI市场空间足够广阔,短期流量、订单、细分赛道红利只是 “芝麻”,攻克通用人工智能才是终极目标。
但是,盲目铺开多条战线、追逐各类风口,只会分散算力、人才与资金资源。
因此,深度求索取舍了视频生成、消费级超级App等赛道,收拢全部资源聚焦AGI主线,拒绝陷入全面开战的资金消耗战。
一边是全球科技巨头和国内大厂不惜消耗自有现金流,开启无上限的AI资本竞赛,追求抢占短期赛道份额;另一边是AI创业者,信奉 “克制哲学”,主动做减法,把提升终极目标的成功率放在首位。
事实上,这两种路径都没有绝对对错,却抛出这样一个命题,AI终局竞赛,究竟是依靠持续不断地资金投入堆出领先优势,还是依靠极致聚焦、避开无序消耗,稳步抵达终点?

AI确实是未来,但可以肯定的是,如果这场烧钱游戏的终局,是以巨头们的集体财务透支为代价,那等潮水退了,扛不住的,将远不止谷歌和特斯拉。
(头图由AI生成。)
(声明:本文仅作为信息交流,不构成任何投资参考建议。)
更多精彩内容,关注钛媒体微信号(ID:taimeiti),或者下载钛媒体App

(本文作者为 新质动能,钛媒体经授权发布)
文 | 新质动能
梅西走下世界杯赛场,变身硅谷投资人。
北京时间7月19日,2026年世界杯落下帷幕。纽约新泽西体育场里,西班牙加时1比0击败阿根廷,捧起大力神杯,39岁的梅西无缘卫冕,这很可能是他职业生涯的最后一届世界杯。
绿茵场上的故事似乎正在走向尾声,但很少有人留意到,梅西的另一重身份正在被重新定义。今年2月,他名下的风投平台Play Time出手,参投了“AI教母”李飞飞创办的空间智能公司World Labs,投资方名单里,还站着英伟达、AMD这样的硅谷巨头。
事实上,梅西的商业版图远比外界想象得庞大。据《福布斯》今年6月的统计,梅西个人净资产已突破11亿美元,年度总收入高达1.4亿美元,场内场外收入几乎各占一半,是现役运动员中仅有的四位“十亿美元俱乐部””成员之一。
而在他之前,克里斯蒂亚诺·罗纳尔多(C罗)早已入股AI搜索公司Perplexity;姆巴佩投资了估值近60亿美元的数字健康独角兽;就连NBA球星也没闲着,从沙奎尔·奥尼尔到卡梅罗·安东尼,一批体坛巨星正扎堆涌入科技投资圈。
当球王们脱下球衣、走进硅谷的会议室,他们究竟看中了什么样的生意?
梅西跨界要从2022年10月说起。彼时正值卡塔尔世界杯前夕,梅西在旧金山成立了一家投资公司Play Time,slogan写着“在体育与科技的交汇处”。
Play Time首期基金规模约2亿美元,投资方向覆盖全球体育和科技领域,梅西集团当时的声明里提到,这家公司会投资各阶段的初创企业,也会考虑帮创始人搭建足球科技公司,甚至入股球队。
真正让Play Time出圈的,是它今年2月出手,参投了李飞飞创办的World Labs的10亿美元新一轮融资,与英伟达、AMD这样的科技巨头同列股东名单。梅西和李飞飞就这样“跨次元”合作了。
梅西的成就无需赘述:8次金球奖、4次欧冠冠军、10次西甲冠军、1次世界杯冠军、2次美洲杯冠军,几乎把一个球员能拿的荣誉拿了个遍,被无数人称为“史上最伟大的足球运动员”。
李飞飞被称为“AI教母”,她曾在斯坦福大学人工智能实验室,发起了改变整个行业进程的ImageNet项目,用数百万张标注图像为深度学习在计算机视觉领域的爆发奠定了基石。
2024年,李飞飞离开斯坦福,创办World Labs,一头扎进“空间智能”这个新赛道,目标是让AI不仅能识别图像,更能像人类一样理解、推理并交互三维物理世界。
World Labs的成长速度堪称惊人,成立当月就完成首轮融资,估值已达2亿美元;短短两三个月后,再获1亿美元融资,估值跃升至10亿美元,正式跻身独角兽行列。到今年2月完成10亿美元新一轮融资时,公司估值已经冲上50亿美元。而此时,距离李飞飞创业不过短短16个月。
而Play Time正是这轮融资名单里的一员,某种程度上,这也意味着梅西的投资平台正式打入了硅谷科技圈的核心地带。
翻开Play Time的公开投资组合会发现,这家机构的野心远不止一笔投资。除了World Labs,其早期还投过足球游戏平台Matchday、足球收藏品平台AC Momento,此后重心逐渐转向AI与机器人赛道,出手过AI数据标注平台SuperAnnotate、三维可视化工具Intangible、物理世界基础模型公司Perceptron、机器人开发商Field AI,以及语音AI生成服务Fish Audio等。
其中Field AI背后,同样站着英伟达、比尔·盖茨、贝索斯等重量级投资人。
Pitchbook数据显示,Play Time自2022年底成立以来已出手10次,投资路径已经覆盖了AI底层工具、实体机器人两大前沿方向,早已打破了体育明星跨界投资只会碰地产、餐饮、潮牌的刻板印象。
绿茵场的胜负终有落幕之时,而梅西在科技行业的投资才刚刚开始。
梅西不是唯一一个把目光投向AI的球星。如果说梅西走的是机构化的VC路线,那么他的老对手C罗,则更像是一位活跃的个人天使投资人。
2025年12月5日,C罗通过社交媒体宣布已投资美国AI初创公司Perplexity,成为该公司股东之一。
Perplexity成立于2022年,由前OpenAI、前谷歌DeepMind工程师创立,主打“对话式搜索”,2025年9月完成2亿美元融资,估值约200亿美元。
投资落地后,Perplexity还在搜索引擎上线了“Perplexity x CR7”互动专区,全球粉丝可以就C罗职业生涯的档案数据向AI提问。
这不是C罗第一次向科技赛道下注。今年上半年,他追加投资了可穿戴健康设备公司WHOOP,这家公司主打无屏化的健康与运动监测,目前估值已达100亿美元;他还曾持有个性化补品公司Bioniq的股份,后者已被康宝莱收购。
Pitchbook数据显示,C罗以个人名义投资的创业公司已有10家,2022年之后,他大致保持每年出手3家左右的节奏。
据《福布斯》今年6月的统计,过去12个月C罗以3亿美元总收入登顶全球运动员收入榜,个人身家估值达12亿美元,正式跻身“十亿美元俱乐部”,与梅西、詹姆斯、伍兹并列现役运动员中仅有的四位亿万富豪。
纵观整个职业生涯,C罗税前总收入约21亿美元,超越梅西的约18亿美元,也高于伍兹近20亿美元的职业生涯总收入。
如果说科技赛道是C罗近两年才重仓押注的新战场,那么体育产业则是他财富版图里厚实的基本盘。
2025年8月,C罗与利雅得胜利完成续约,换来俱乐部15%股权,成为这家沙特豪门的第二大股东;同年11月27日,他又宣布投资西班牙综合格斗赛事品牌WOW FC,把体育影响力从球场延伸到了格斗擂台。
而C罗的个人品牌“CR7”,更是撑起了服装、鞋履、香水、酒店的完整矩阵。Pestana CR7酒店开到了马德拉岛丰沙尔、里斯本、马德里、纽约和马拉喀什五地,他的Instagram粉丝数超过6.69亿,堪称一个人的分发渠道;跟耐克签下的终身合约价值超10亿美元,2024年他更以2.6亿美元总收入蝉联Sportico全球运动员收入榜第一。
整体来看,C罗的投资风格呈现出“不控股、快周转”的特点,用他自己的话说,就是不依靠单场进球,而是持续布局下一个得分点。
梅西和C罗的选择并非孤例。放眼整个体坛,一批顶尖运动员正在职业生涯中后期主动叩开VC圈的大门,而且各有各的打法。
比梅西和C罗年轻一大截的姆巴佩,走的是一条“既要控股、又要投人”的混合路线。
2024年,25岁的姆巴佩通过拍卖,以1500万欧元拿下法乙球队卡昂80%的股份,一举成为欧洲足坛最年轻的俱乐部老板;2025年,他又摇身一变成了国际帆船大奖赛法国队的小股东。
而在科技领域,姆巴佩今年3月参与了法国数字健康保险公司Alan新一轮1亿欧元融资,这笔投资以50亿欧元估值完成,姆巴佩本人还将以品牌大使身份参与公司运营。这家成立于2016年的公司,目前在四个国家坐拥110万会员,2025年营收达7.85亿欧元,是当之无愧的独角兽。
同样出自法国“黄金一代”的安托万·格列兹曼,则选了一条最省心的路:不当GP,只当LP。他出资的Athletico Ventures有个颇为“佛系”的打法:不主动挖项目,只跟投顶级机构领投的交易,单笔出资15万至50万欧元。
靠着这套逻辑,这家机构已经投出了足球游戏公司Sorare、智能健康戒指Oura等多家独角兽项目,格列兹曼与英格兰球员埃里克·戴尔等约40位运动员一同成为这家机构的出资人。
篮球圈的故事同样精彩。19年NBA生涯拿下2.86亿美元薪资的“大鲨鱼”沙奎尔·奥尼尔,去年10月加入另类投资公司Jacmel Partners担任创始合伙人,把目光投向交通、能源、数字基建这些听起来跟篮球毫不沾边的领域。
奥尼尔早年还曾押注谷歌、并成为品牌收购商Authentic Brands Group的第二大个人股东。
今年5月,另一位篮球名人堂成员卡梅罗·安东尼,则把目光投向了好莱坞。他投资了华人创业者Cecilia Shen创办的AI影视公司Utopai Studios,助力这家估值已达10亿美元的公司打造AI影视内容。
“我刚进NBA的时候,大家讨论的是豪车和名牌衣服,现在大家讨论的都是谁投了哪家科技公司。”NBA球星安德烈·伊戈达拉的这句话,或许最能概括这一代运动员的心态转变。
这些名字散落在不同项目、不同国家,却在做同一件事:把职业生涯积累的现金、影响力和行业关系,转化成可以长期持有的资产。
当然,热闹背后也有隐忧。退役球星中也不乏斯科蒂·皮蓬、安东尼·沃克这些投资失利,甚至申请破产的先例。
梅西投了李飞飞,C罗投了Perplexity,越来越多体育明星进入一级市场;他们不再满足于只做技术浪潮的代言人,他们开始成为技术浪潮的参与者。
参考资料:
《梅西投了李飞飞》,投资界;
《梅西变身硅谷投资人,投了”AI教母”李飞飞》,硅基见闻;
《10亿美元先生:梅西的「球王生意」》,中国企业家杂志;
《李飞飞,刚刚又融70亿》,投资界;
《又有NBA球星做投资人了》,东四十条资本;
《NBA球星投资都流向哪个领域 詹皇科比赚翻也有人破产》,腾讯NBA;
《梅西投地产,C罗押AI,姆巴佩买球队:世界杯球星的钱去哪了?》,国际金融报;
《顶级球星是如何做VC的?》,投中嘉川;
《100亿身家”足坛首富”,投了最火AI独角兽》,融中财经;
《NBA球星安东尼刚投了一位25岁华人女孩》,福布斯中国。

更多精彩内容,关注钛媒体微信号(ID:taimeiti),或者下载钛媒体App